Reliable US payroll depends on accurate inputs, timely processing, and a team that knows who is responsible for each step. Federal requirements are only part of the picture; state and local obligations can matter too. The software needs to reflect the workforce you actually employ.
Start with the changes that affect this pay run
A new employee, a move to another location, a working-hours change, or a bonus can alter what payroll needs to process. Check the approved source, effective date, and whether the change arrived before cutoff. Do not assume a correct employee profile means every downstream system has received the update.
Keep tax and filing responsibilities visible when a provider is involved. The IRS explains that using a payroll service provider generally leaves the employer responsible for federal tax liabilities. Establish how your team can check payments and receive notices independently.
Have payroll specialists confirm the rules for the locations and employment arrangements in scope. The point is to configure and check the actual obligations, not to rely on a generic “US compliant” product claim.
Who supplies and approves the payroll information?
Identify who approves hours, pay changes, deductions, employee classifications, and work-location updates. Record effective dates and cutoffs. Changes should reach payroll through an approved process rather than informal messages that are difficult to reconcile.
Confirm the employing entity and relevant work locations. A change in where someone works can require review; do not assume that the employee’s mailing address settles every payroll question.
Check tax and filing responsibilities
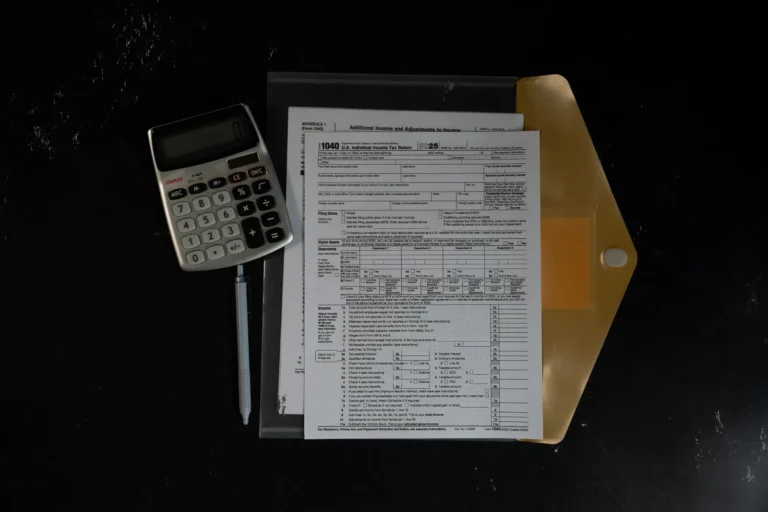
The IRS employment tax guidance explains federal employment tax topics. Use current official guidance and professional advice to establish your actual obligations, schedules, and responsibilities. Software settings should reflect those decisions, not substitute for them.
If a provider performs payroll tasks, document who prepares, reviews, authorizes, and verifies each step. Outsourcing should not leave both parties assuming the other checked a filing or payment.
Reconcile before approval
- Compare employee counts with the approved population.
- Review unusual changes in earnings, deductions, and net pay.
- Investigate rejected or duplicated inputs.
- Check starters, leavers, and retroactive adjustments.
- Preserve approval and correction evidence.
Use thresholds as prompts for investigation rather than automatic declarations of error. Some large changes are legitimate; some small recurring differences reveal a process problem.
The records payroll needs
The US Department of Labor recordkeeping guidance covers federal FLSA recordkeeping requirements. Determine the applicable retention rules across your records with the relevant specialists, and configure the system accordingly. Avoid applying one period to every document simply because it is associated with payroll.
Limit access to sensitive information and test whether historical records remain usable after a system change.
Control changes to the system
Test configuration and integration changes before they affect live pay. Record who approved them and how results were checked. Maintain a plan for failed transfers or urgent corrections.
Connect these controls to payroll integration and the payroll management process. The aim is a payroll operation whose inputs, calculations, approvals, and records can be explained, with jurisdiction-specific decisions reviewed by people qualified to make them.
Make corrections easier to trace
When a pay result changes, retain the reason, approval, and connection to the original input. Review unusual movements against the previous period without assuming that every difference is an error.
Practice an urgent correction before an employee needs one. Who makes the decision, who communicates with the employee, and which records are updated afterward? A reliable payroll process should handle an exception without requiring the whole team to reconstruct what happened from a chain of messages.
Updated October 4, 2026.